
THINKING ABOUT A SHORT SALE? CALL A FREE, GOVERNMENT-APPROVED COUNSELOR BEFORE YOU SIGN ANYTHING.
If you're behind on your mortgage, or your home is worth less than you owe, you may have been told about a "short sale." You may also have been told a lot of other things by people who want your money.
Here's the place to start instead. For foreclosure prevention, the counseling is free.
What a short sale is. According to the Consumer Financial Protection Bureau (CFPB), a short sale is when you sell your home for less than you owe, with your mortgage servicer's approval, and the servicer forgives the difference. You're responsible for finding a buyer. If you have other mortgages on the home, you need approval, and forgiveness of what you owe, from those servicers too.
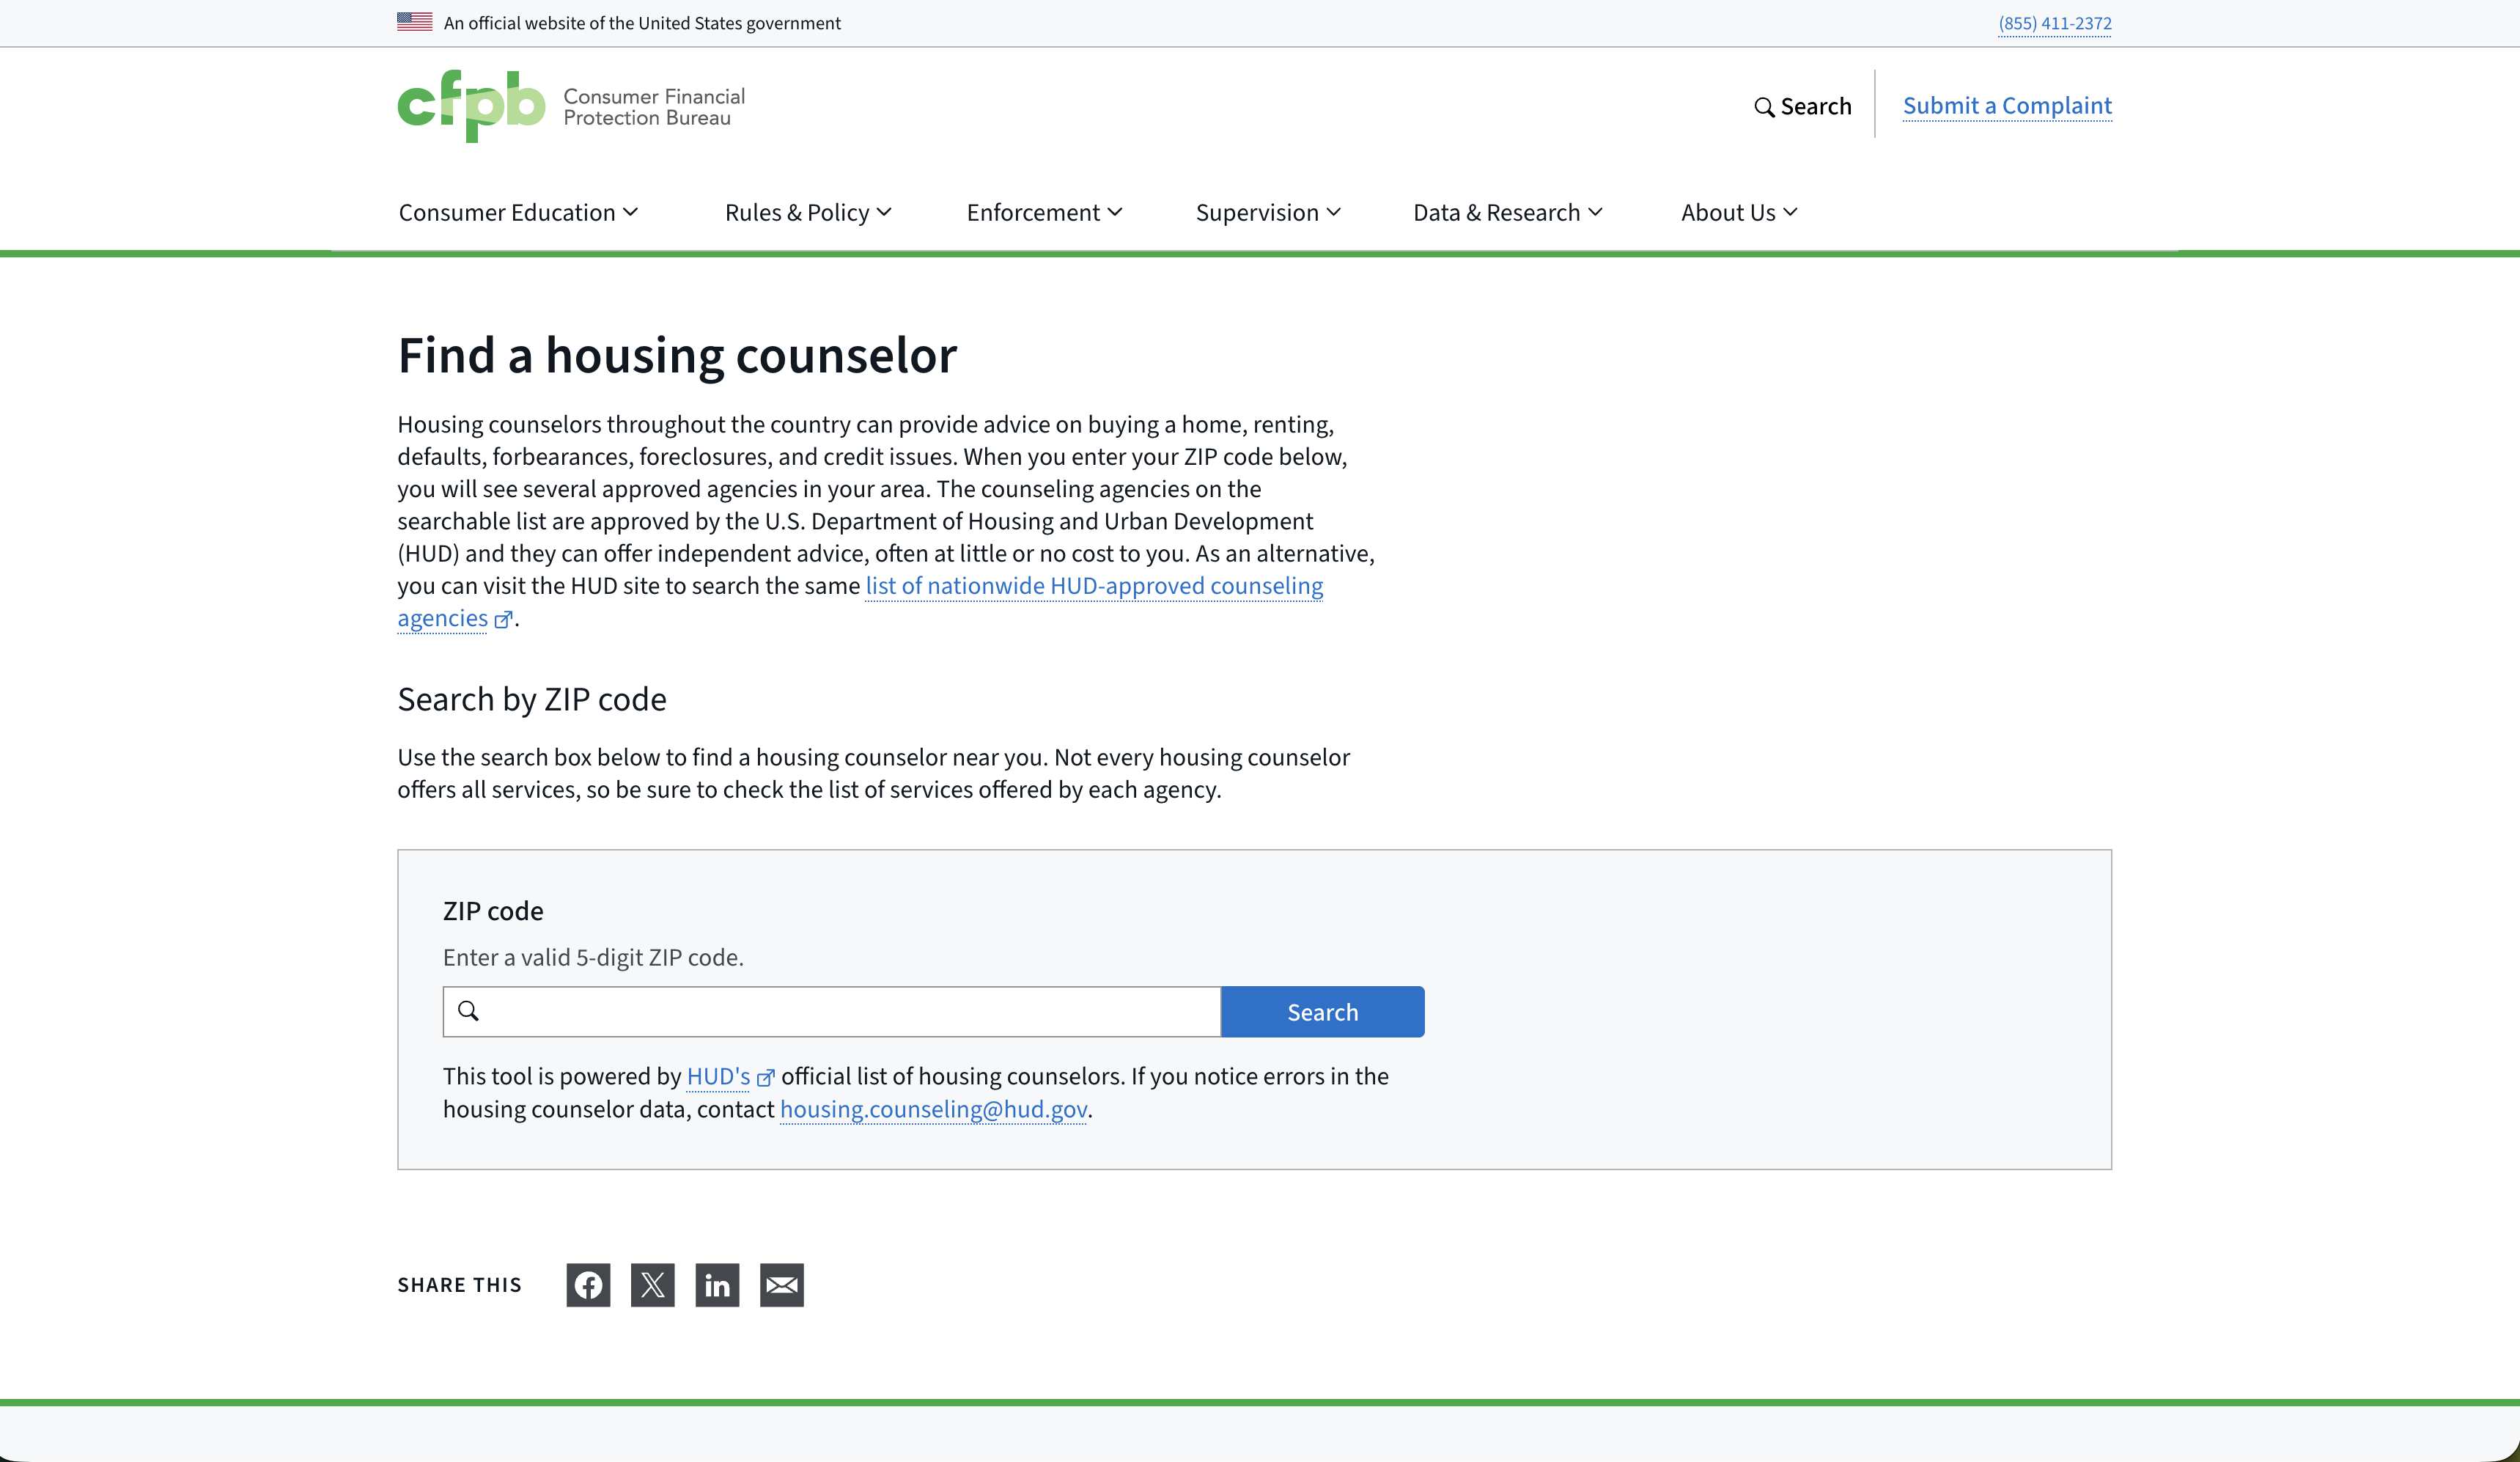
The tool. The CFPB's Find a Housing Counselor page lets you enter your ZIP code and see HUD-approved housing counseling agencies near you. HUD is the US Department of Housing and Urban Development. The list is powered by HUD's own official list of counselors, and the agencies are nonprofit or government organizations. The CFPB says HUD-approved agencies provide foreclosure-prevention counseling free of charge. Not every counselor offers every service, so check the services listed for each agency. The tool's own page describes the advice as available "often at little or no cost to you," so ask about fees up front. You can also call (800) 569-4287 and enter your ZIP code, or call the CFPB at (855) 411-2372. To double-check that an agency is really HUD-approved, HUD says to look it up at hud.gov/findacounselor.
What a counselor does. A HUD-approved counselor can help you assess your finances, understand your options, talk with your servicer, and put together a plan. Those options can include a loan modification, a repayment plan, a short sale, or giving the home back to your lender in a "deed in lieu of foreclosure." When you call, expect to be asked about your loan (the amount you owe and the date of your last payment) and for papers like pay stubs, tax returns, recent bank statements, and other monthly bills. The CFPB is also blunt about one thing: a counselor can't promise you'll keep your home.
How a short sale actually happens, per the CFPB. You request a loss mitigation application from your servicer, send in a complete application with supporting documents, and get approval from both your servicer and the owner of your loan. Make sure you understand the terms of your specific short sale, including the tax effects.
Timing matters. The CFPB says your servicer generally can't make a first notice or filing for foreclosure until you're more than 120 days behind. It also says that if you submit a complete application for mortgage help early enough, the servicer can't start foreclosure while it evaluates you.
The warning that goes with all of this. Scammers target homeowners in trouble, sometimes charging thousands of dollars for false promises. The CFPB's signs of a foreclosure scam include a company that guarantees it will get your loan changed and someone telling you to stop paying your mortgage. Its advice is that you shouldn't have to pay anyone to help you avoid foreclosure, because the help is available at no cost from your servicer or a HUD-approved counselor. By its account, mortgage relief companies aren't allowed to collect fees until they give you a written offer from your servicer that you decide is acceptable.
Honest notes: this is general information, not legal or tax advice. Forgiven debt can have tax effects, and tax rules on this have changed over the years, so talk to a tax professional before you close. State laws differ on what a lender can pursue afterward, so make sure any approval spells out what happens to the leftover balance, and consider a real estate attorney. This is for US homeowners.
If you're in this spot, or you know someone who is, the counseling is free. Make the call before you sign anything.
READY? HERE IT IS.
 oh, one more thing before you go — word on the street is you missed past Rubbernecks and you're falling behind. The archive.
If you click and buy something, we may earn a small cut. If it's boring, we don't feature it.

GET TOMORROW'S
JAW-DROPPER.
One site. Every day. Free. In your inbox. No garbage. Unsubscribe whenever.
MORE LIKE THIS
🐔 YOU THINK THIS IS THE ONLY ONE?
THERE ARE HIDDEN GEMS
YOU HAVEN'T SEEN YET.
A new jaw-dropper every day. Go dig through the archive — there's something in there that will wreck you.